
DANA Indonesia Digital Wallet
- Rating
- 4.5
- Downloads
- 100.00M
- Content Rating
- Everyone
DANA Indonesia Digital Wallet - Screenshots
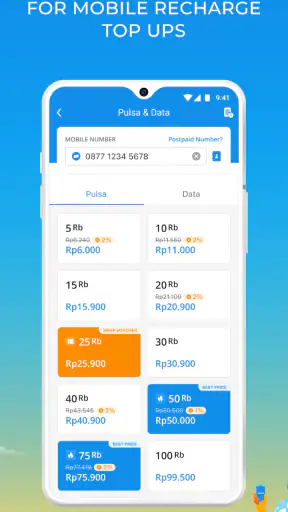
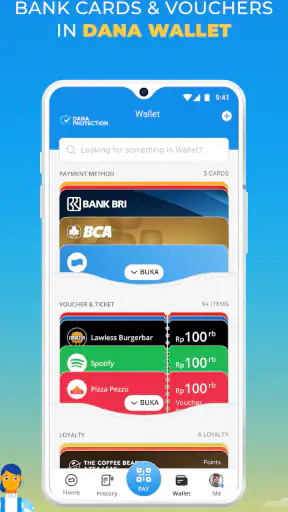
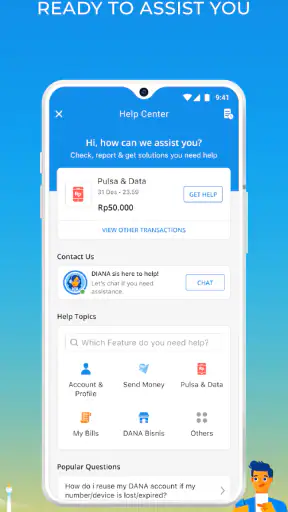
DANA Indonesia Digital Wallet - Description
- App Name
- DANA Indonesia Digital Wallet
- Package Name
- id.dana
- Developer
- PT Espay Debit Indonesia Koe
- Category
- Finance
- Last Updated
- May 7, 2019
- Version
- 2.128.0
Analysis by TrendiApps
I find a digital wallet most useful when it takes a routine payment out of my way, rather than asking me to rethink how I handle every part of my money. That is the lens I use for DANA Indonesia: it is a finance app from PT Espay Debit Indonesia Koe, and its appeal is practical, everyday cashless use. It is free to install, has an average rating of 4.5 from around 10 million ratings, and has passed 100 million installs. Those figures suggest a widely used service, but what matters more to me is whether it can fit naturally into a person’s payment habits.
Start with a simple, repeatable routine
I would begin by treating DANA as one payment option, not as a reason to abandon every other way of paying. Add it to the moments where a wallet is genuinely handy: a quick purchase, a bill, or a transfer you already intend to make. That makes it easier to notice whether it saves time without losing track of what you spend. The app is currently version 2.128.0, and it requires Android 5.1 or later; its content rating is Everyone.
A useful habit is to pause before confirming a payment and check the recipient and amount rather than relying on speed alone. That small check matters particularly when you are paying in a busy place or handling several expenses at once. I also prefer to keep a separate record of larger or recurring commitments in the place where I normally track my budget. A wallet can make payment convenient, but convenience by itself is not a spending plan.
Streamlined Finance Management
What I love about DANA Indonesia is how it simplifies financial transactions. As someone who constantly juggles between different payment methods, having an e-wallet that consolidates everything into one place is a game-changer. The app supports a wide range of transactions, from paying bills and transferring money to purchasing online. It’s available for free and is compatible with any device running on Android 5.1 and above, making it accessible to a broad audience.
One of the hidden gems I discovered is the app's ability to store loyalty cards. This means I can ditch the physical clutter in my wallet and have all my rewards in one digital space. Plus, the app's interface is intuitive. Even if you're not tech-savvy, navigating through its features is a straightforward experience.
Settings and habits that make a difference
I would spend a minute reviewing the app’s available account and security settings before making it part of a daily routine. Keep the phone itself protected, use a screen lock, and avoid approving a payment while distracted. I do not assume every wallet has the same controls or that a particular control works identically on every phone, so it is better to check what is actually available in your own version than to follow a generic setup checklist blindly.
Loyalty cards are most helpful when I add only the ones I use regularly. A digital collection can become just as cluttered as a physical wallet if every occasional card goes in and never comes out. I would also make a habit of checking whether a shop can accept the payment method before joining a queue; having a wallet ready is useful, but it does not guarantee every merchant will accept it.
Stories You Might Enjoy
Gallery’s Quiet Advantage: It’s Already Where Your Photos Live
Universal TV Remote Control Gets the Basics Right, but Setup Needs Work
Instagram’s Real Advantage Is Keeping Every Kind of Attention in One Place
Shadow Fight 3 Makes Every Duel a Lesson in Timing
Pizza Ready! Makes the Dinner Rush Feel Good—Until It Doesn’t
AliExpress Makes Curiosity Shopping Worth the Search
Real-Life Use Cases
Imagine this: You're at a restaurant with friends, and the bill arrives. Instead of fumbling through cash or multiple card payments, you can quickly split and send your share via DANA. This scenario is a perfect example of how the app integrates into everyday life, making social spending seamless.
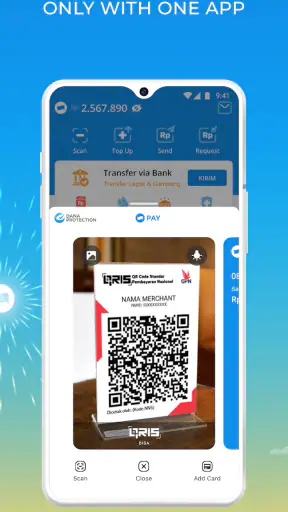
Another impressive feature is the QR code payment option. It’s not only fast but also secure. I’ve used it several times at local stores and food stalls, and it significantly cuts down the time spent at checkout. The app's security protocols ensure that my financial data is safe, which is always a top concern for digital transactions.
Faster patterns for ordinary errands
For a repeat purchase, the time-saving part is not tapping quickly; it is having a calm, familiar sequence. I would open the wallet before reaching the counter, confirm that the displayed amount matches the purchase, and then complete the QR payment without juggling other tasks. At a crowded food stall, for instance, this avoids searching for cash while holding a drink or trying to remember what friends ordered. If the QR option is unavailable or the connection is unreliable, I would switch to a backup payment method rather than hold up the line.
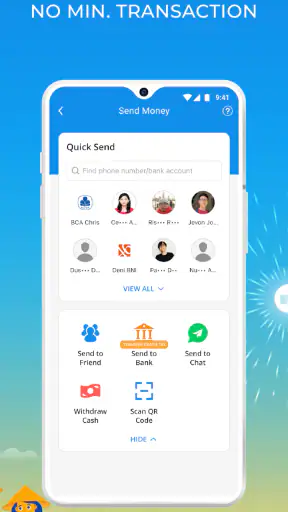
For shared costs, I find it clearer to agree on the amount first and send each person’s share separately, rather than trying to settle a vague total later. A short note in a personal budget or message can help everyone remember what a transfer covered. This is a small workflow, not a special feature, but it reduces the chance of confusing a restaurant payment with another transfer. I would not assume that a wallet can automatically resolve every group expense or that another person can receive money through the same route.
Bill payments can also be easier to manage when I do them at a predictable time, such as during a weekly money check-in, rather than waiting until the last moment. Before confirming, I would compare the bill details with the amount I expect to pay. That extra moment is useful in any payment app, especially when a transaction is difficult to reverse once sent. For a payment that is urgent or unusually large, I would favor the method whose confirmation and support process I understand best.
Who Will Benefit the Most?
If you’re someone who values convenience and efficiency in managing finances, this app is definitely worth trying. It’s especially beneficial for those who frequently engage in cashless transactions. However, if you prefer traditional banking methods with physical documentation, you might find this digital approach a bit overwhelming.
Parents will appreciate the app's simplicity. It’s an excellent tool to teach teenagers about financial responsibility, allowing them to manage a digital allowance without the risk of overspending. The app's age rating of "Everyone" ensures it's appropriate for all users.
Where a wallet is not the right tool
I would be more cautious about making DANA the only way I can pay. A phone can run low on battery, mobile service can falter, or a merchant may not accept the method I planned to use. Keeping a physical card or a modest amount of cash as backup is sensible, particularly when travelling around town or making a purchase I cannot postpone. That is not a criticism unique to this app; it is a trade-off inherent in relying on a phone for payment.
It is also worth separating payment convenience from banking needs. Someone who wants detailed account statements, a long-term savings setup, or branch-based assistance may be better served by a conventional bank app or in-person banking as their primary tool. DANA makes most sense as a practical layer for local spending and transfers, not as a replacement for every financial service. If you are uncomfortable managing money on a phone, there is no need to force the switch.
Comparing Alternatives
While there are other e-wallets in the market, DANA Indonesia's extensive user base and high ratings—over 100 million installs—speak volumes. It holds its ground well against competitors like GoPay and OVO by offering a more comprehensive service range and a user-friendly interface. However, it's worth noting that some users might prefer apps with more international transaction capabilities, which is an area where DANA can improve.
For those who travel frequently or make international purchases, considering other apps that offer better foreign transaction options might be wise. But for everyday transactions and local uses, DANA Indonesia is hard to beat.
In practical terms, I would choose among wallets based on where I actually pay, which people I need to send money to, and how easily I can verify a transaction—not on the size of an app’s feature list. If friends or regular local merchants already use DANA, that can make it more convenient than switching between several wallets. If your usual shops favor another service, or your priority is international use, the alternative that fits those needs is the better choice. Keeping more than one payment option can be useful, though it also means checking balances and activity in multiple places.
Limits worth planning around
One practical question is whether I can use the wallet for every purchase I have in mind. I would not assume so: acceptance depends on the merchant and the payment route available at the time. For an unfamiliar shop, I would ask before ordering or keep another way to pay ready. The same cautious approach applies to transfers: double-check the recipient details, and do not treat a fast confirmation as proof that a mistaken payment can be undone.
Another question is whether the app suits international spending. I would not make it my first choice for a trip or a foreign purchase if those are my main needs; a payment product designed around international use may be a more dependable fit. For ordinary local transactions, by contrast, a wallet can reduce the need to carry cash for every small purchase. The right choice depends on the payment situations that actually make up your week.
Security also depends on the way I use the phone, not just on the wallet. I would avoid sharing access, protect the device, and review transactions often enough to notice anything unexpected. If a payment appears delayed, I would check its status before attempting it again; repeating a payment too quickly can create uncertainty about whether the first attempt completed. That is a useful habit with any digital wallet, especially when a queue or deadline makes it tempting to tap twice.
A Few Limitations
Despite its many strengths, I’ve encountered occasional hiccups with the app’s server during peak times, which can delay transactions slightly. Although these instances are rare, it’s something to keep in mind if you often make urgent payments.
Moreover, while the app is free, certain advanced features might require you to upgrade your account. But for basic transactions, the free version is more than sufficient.
My advice for reducing that friction is simple: do not leave a time-critical payment until the final minute, and keep another payment route available for emergencies. If an attempted transaction is pending, I would verify the result before trying again. That avoids turning a brief service delay into a duplicate payment or an avoidable argument about whether the money went through. This is also why I would not use any one wallet as the sole solution for a deadline-sensitive expense.
Someone deciding whether to try it may also wonder if they need to be especially experienced with technology. I do not think so: the everyday idea of choosing a payment, checking the details, and confirming it is familiar. The more important question is whether the wallet works with the merchants and people you deal with. Starting with a small, routine purchase is a sensible way to learn the flow before relying on it for a larger or more important transaction.
A considered everyday choice
In conclusion, DANA Indonesia offers a robust platform for managing everyday finances with ease. Whether you're splitting bills, paying for groceries, or teaching your kids about money, it’s a versatile tool that fits various needs. Just be mindful of its limitations if you plan to use it extensively for international transactions. Overall, it’s a solid choice for anyone looking to embrace the convenience of a cashless society.
For me, the best way to get value from it is to keep the routine modest: use it where it makes local payments simpler, review each transaction, and maintain a backup for the situations a phone wallet cannot solve. That combination of convenience and caution is more useful than expecting any app to handle every financial task. If that matches how you pay, DANA is worth considering; if you need international flexibility or prefer paper-based control, another option will likely suit you better.
DANA Indonesia Digital Wallet FAQ
What is DANA, and how does it work?
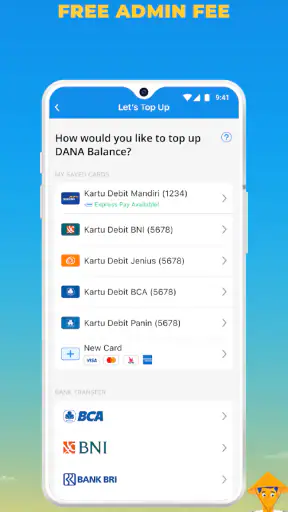
DANA is a digital wallet application designed to facilitate cashless transactions in Indonesia. It allows users to store money digitally, pay bills, transfer funds, and make in-app purchases securely. Users can top up their DANA wallet through various methods such as bank transfer, credit card, or through partner merchants.
Is DANA safe to use for online transactions?
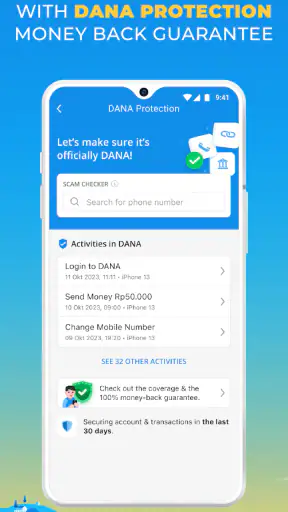
Yes, DANA is equipped with advanced security features to protect users’ financial data. It uses encryption and secure authentication methods to ensure that transactions are safe. Additionally, users receive real-time notifications for all transactions, adding an extra layer of security and transparency.
Can I use DANA without an internet connection?
To perform most transactions, an internet connection is required. However, users can access their transaction history and view their balance offline. For added convenience, users should ensure they have a reliable internet connection to make full use of DANA's features, such as paying bills and transferring money.
What are the fees associated with using DANA?
DANA offers many of its services for free, including transfers between DANA users and payments to partner merchants. However, certain transactions, like withdrawals to a bank account, may incur fees. It’s advisable to check the app for the most current fee structure before proceeding with any transaction.
How can I resolve issues with my DANA account?
If you encounter any issues with your DANA account, you can contact their customer service through the app or via their official website. They offer support through email, phone, and live chat. Additionally, the app provides a comprehensive help section with FAQs and guides to assist with common problems.
Pros
- User-friendly interface makes navigation easy.
- Supports a wide range of payment methods.
- Offers cashback and discounts regularly.
- Secure transactions with multi-layer protection.
- Quick customer support response time.
Cons
- Limited international transaction support.
- Occasional app slowdowns during peak times.
- Requires internet for most features.
- Some features restricted to premium users.
- Verification process can be lengthy.


